The loan funds on a Friday afternoon. Your clients get the keys, take the photo in front of the sold sign, and tag everyone except you. They are thrilled, grateful, and gone. Six months later they refer a friend to a different broker, because the friend asked for a name and your client could not remember yours. This is the mortgage broker’s review problem in one scene: you guide people through the biggest financial decision of their lives, earn real gratitude, and then lose the evidence. Borrowers are happy at exactly two moments, pre-approval and closing day, and if you do not ask at those moments, you do not get reviews. This guide lays out the two ask-milestones, the automated post-closing text workflow, response templates for the complaints brokers get, and how review volume feeds the agent referrals that build a mortgage business.
The quick answer
- Ask at two milestones: pre-approval day and the day the loan funds. Those are the two moments borrowers feel real relief and gratitude.
- Automate the post-closing text: trigger the review request from the funded-loan status in your pipeline so it goes out even when you are buried in files.
- Text, not email: borrowers open texts. A personal message with a direct Google link outperforms any email drip by multiples.
- Build the ask into agent partnerships: ask referring agents to request the review too, and review the agent’s clients first when you can.
- Reply to every review: short replies to positives, calm template replies to complaints about rates or delays. Replies are public sales material.
- Reviews feed referrals: agents check your Google profile before trusting you with their buyers, and borrowers check it before trusting you with their loan.
Why mortgage brokers struggle with reviews
Most trades sell repeat business. Mortgages are nearly one-time transactions: the average borrower buys again or refinances every five to seven years, and the relationship goes quiet in between. The loan process itself is stressful, full of document requests and waiting, which means the broker is associated with anxiety until the very end. By the time gratitude arrives, the file is closed and the team has moved on. The fix starts with making it obvious who to review: your Google Business Profile should carry your name and role clearly, and every ask should point to that one profile. Then build the ask into the loan milestones, because milestones are the only moments that cut through the stress.
The two milestones that produce reviews
Borrowers feel two genuine highs during a loan. Miss both, and you are asking a stranger for a favor months later.
Milestone 1: pre-approval day
Pre-approval is the moment a renter becomes a buyer. The client just learned they can actually buy the house, and the relief is real. Ask right there, on the call or in the meeting where you deliver the pre-approval letter. “You are officially a buyer now. When we get you to closing, a Google review from you would mean a lot to my business. I will send the link once we fund.” You are planting the seed, not collecting the review yet. The borrower now expects the request, and the closing-day ask feels like a promise kept instead of a surprise. For purchase loans that fall through, which happens, do not ask. Only collect reviews from funded loans and successful refinances.
Milestone 2: the day the loan funds
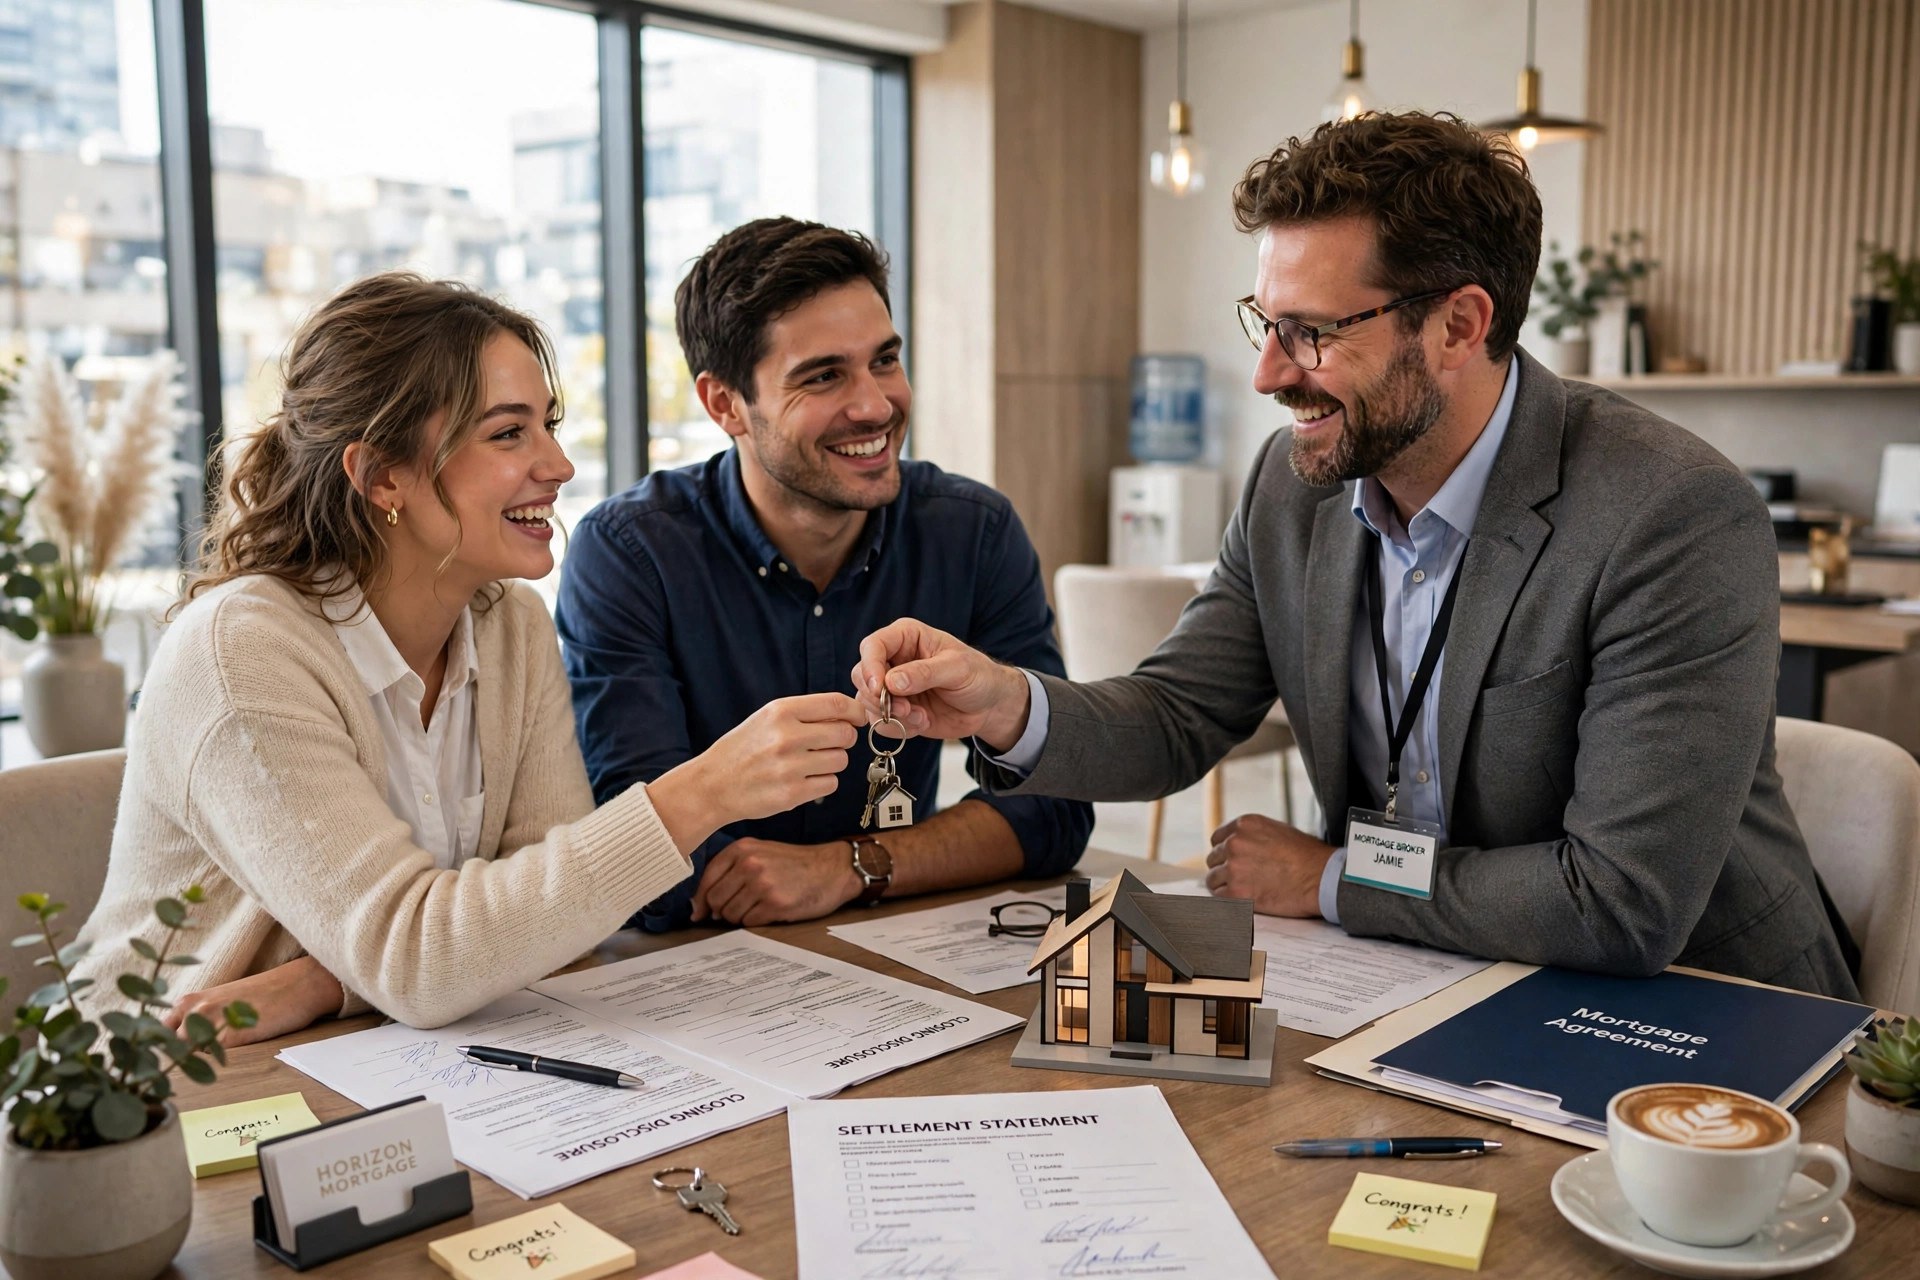
Funding day beats closing day for the ask, because funding is when the money moves and the deal is truly done. Call or text the borrower the day the loan funds, congratulate them, and make the ask in the same breath. “Your loan funded today, congratulations, homeowner. I loved working with you on this. Would you leave me a Google review? I will text you the link right now.” Same-day timing matters more than perfect wording. A borrower asked on funding day says yes because the win is fresh. A borrower asked at the 90-day check-in says “sure” and never does it.
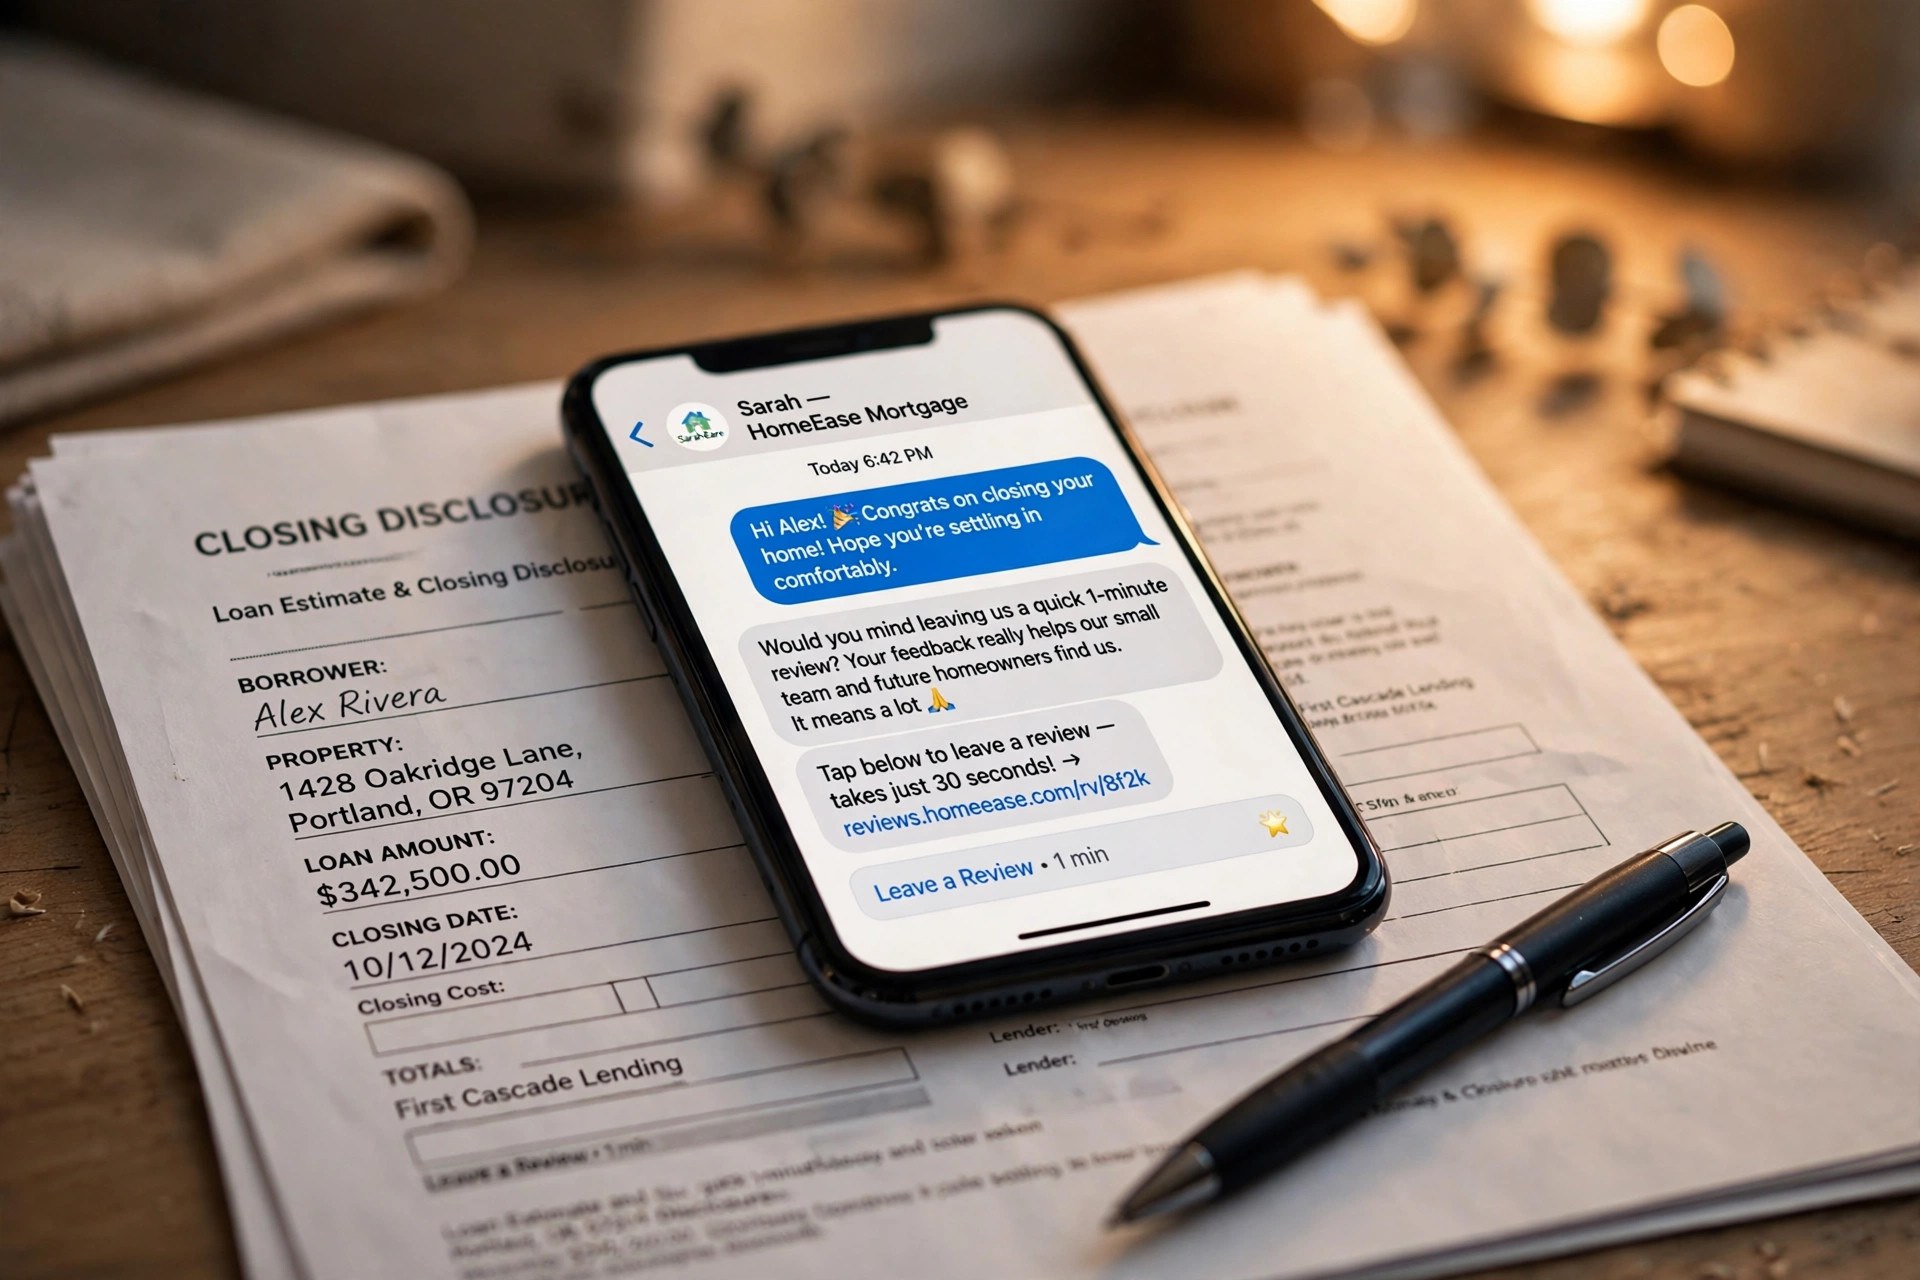
Funding day is the emotional peak. Ask in person or by phone, then text the review link within hours.
The automated post-closing workflow
You will not remember to text every borrower on funding day. Pipeline volume, rate locks expiring, and underwriting fires will bury the manual habit within a month. Build the trigger in your CRM or loan pipeline: when the loan status changes to funded, the borrower enters a short review sequence automatically.
| Step | Timing | What happens |
|---|---|---|
| Congratulations call | Funding day | Personal call from the loan officer, congratulations plus the verbal review ask |
| Review text | Same day, after the call | Text with the borrower’s name, the loan officer’s name, and the direct Google review link |
| Follow-up text | 3 days later | One gentle nudge to non-responders, framed as a thank-you for the business |
| Agent loop-in | 5 days later | If no review, ask the referring agent to nudge the shared client |
| Close the loop | 7 days later | Sequence ends. No more asks. The borrower enters the long-term nurture list |
Keep the text personal
Automation should be invisible. Use the loan officer’s name as the sender, reference the specific loan, and keep it short: “Hi James, this is Rachel from Summit Mortgage. So glad we got your loan funded this week. If you have a minute, a Google review would really help my business: [link]. Thank you!” Never send the review link by email alone. Borrowers ignore post-closing emails because their inbox is full of moving checklists. The text arrives on the phone they are using to photograph their new house.
Scripts for every trigger point
Loan officers are not marketers, so give them exact words. These cover the full cycle from pre-approval to the agent follow-up.
The pre-approval plant
“Congratulations, you are pre-approved for [amount]. This is the fun part now, go find the house. When we fund your loan, I am going to ask you for a Google review, because reviews are how borrowers find me. Deal?” Getting a yes now makes the closing ask a formality.
The funding-day ask
“Your loan funded today. You did the hard part, gathering every document I threw at you. I am proud of how smooth this went. Would you do me a favor and leave a Google review? I will text you the link, it takes about a minute.”
The three-day nudge
“Hi [Name], Rachel here. Hope the move is going well. Just floating the review link back to the top of your texts in case the move buried it: [link]. No rush at all, and thank you again for trusting me with the loan.”
The agent partnership ask
Ask your top referring agents to co-own the review process: “When we close one of your buyers together, I will text them for a review on funding day. Would you be willing to mention it too? A review that names both of us helps us both.” Many agents will say yes, because a five-star review of the transaction team lifts their profile too.
Agent partnerships multiply review volume when both sides ask the shared client.
Response templates for broker complaints
Mortgage complaints follow a pattern: rates, delays, communication gaps, and surprise costs at closing. Some of these are market forces, not your fault, but the public reply still has to be graceful. Reply within 48 hours, never discuss loan specifics in public, and move the conversation to a phone call.
Template 1: rate complaints
“Thank you for the feedback, [Name]. Rates move with the market and I know that is frustrating when a quote changes during the process. I would welcome the chance to walk through exactly what happened on your file. Please call me directly at [number]. [Your name].” Do not relitigate the rate in public. Offer the private walkthrough.
Template 2: closing delays
“You are right that your closing took longer than we first estimated, and I am sorry for the stress that caused. Several steps in the process were outside our control, but I should have kept you updated more often. I appreciate you working through it with us. [Your name], [number].” Acknowledge the feeling, own the communication gap.
Template 3: poor communication
“I am sorry we left you guessing, [Name]. Clear updates are part of the job, and we fell short on your file. We have changed our update process since, with check-ins at every milestone. I would value a call to hear more: [number].” The mention of a changed process tells future readers the complaint produced improvement.
Template 4: surprise fees
“Thank you for raising this, [Name]. Closing costs should never be a surprise, and I want to understand where the estimate and the final numbers diverged on your file. Please call me at [number] so I can review it with you line by line.” Specific, calm, and private.
For positive reviews, reply briefly and personally: “Congratulations again, James! Enjoy the new place, and call me anytime you have a mortgage question.” These replies show future borrowers that you stay available after funding. Our guide to responding to negative Google reviews covers the general framework.
How reviews feed agent referrals
Here is the compounding loop that makes reviews a growth channel for brokers rather than just a reputation shield. Real estate agents choose which lender to recommend to their buyers, and agents check Google before they trust you. An agent with a $600,000 buyer will not risk their commission on a broker with 14 reviews and a 3.9 rating. When your profile shows 150-plus reviews at 4.9, agents feel safe, and safe is what gets you on the preferred list.
The second loop runs through borrowers. A borrower who leaves you a five-star review has publicly committed to liking you, which makes them far more likely to refer friends and family. Ask reviewers for referrals directly in your reply: “Thank you! If you know anyone starting the home search, I would love an introduction.” For the broader picture, see our mortgage broker marketing ideas guide, and if missed calls are leaking referrals, our missed-call text-back guide for mortgage brokers covers the safety net.
Your rollout checklist
Set this up once in your CRM and it runs on every funded loan.
- 1Clean up your Google Business Profile. Your name, role, and brokerage clear in the business name field rules allow. Save your direct review link.
- 2Write the pre-approval script. Plant the review expectation on pre-approval day so the funding-day ask feels like a kept promise.
- 3Write the funding-day script. One congratulations call with the verbal ask, made the day the loan funds.
- 4Automate the review text. Trigger on funded-loan status: same-day text with the direct link, one nudge at day three, then stop.
- 5Build the agent loop-in. At day five with no review, ask the referring agent to nudge the shared client.
- 6Load the complaint templates. Rates, delays, communication, and fees, each with a calm reply that moves the talk offline.
- 7Pitch the review partnership to agents. Ask your top five referring agents to co-own the ask, and review them back when deals go well.
- 8Track reviews per funded loan. Aim for 40 to 50 percent capture. Review the number monthly and fix the step that leaks.
Pre-approval day plants the seed. The borrower who expects the ask is the borrower who leaves the review.
Frequently asked questions
When should a mortgage broker ask for a Google review?
At two milestones: plant the expectation on pre-approval day, then ask on the day the loan funds. Funding day beats closing day because the deal is truly done and the relief is fresh. Same-day timing converts far better than a check-in weeks later.
Can mortgage brokers offer incentives for reviews?
No. Google prohibits incentives for reviews, and mortgage regulators take a dim view of anything that looks like paying for endorsements. Ask every funded borrower the same way and earn the reviews with the experience.
How should a broker respond to a review complaining about rates?
Acknowledge the frustration, note that rates move with the market, and offer a private walkthrough of what happened on their file with a direct phone number. Never debate the rate or disclose loan details in a public reply.
Should the review go to the broker or the brokerage?
To the individual broker’s profile whenever possible. Borrowers hire the person, not the brand, and agent partners evaluate you personally. Make sure your profile name clearly shows who you are and what you do.
How do Google reviews help mortgage brokers get agent referrals?
Agents check your profile before trusting you with their buyers. A profile with 100-plus reviews at a high rating makes agents feel safe recommending you, and each new agent relationship can mean several loans a year.
What if a loan falls through? Should I still ask for a review?
No. Only ask borrowers with funded loans or completed refinances. Asking after a dead deal feels tone-deaf, and the review would likely reflect the disappointment of the outcome rather than your service.
How many reviews does a mortgage broker need to stand out?
Crossing 100 reviews with a 4.8-plus rating puts you ahead of most local competitors. After that, review freshness matters more than the total: a steady few each month beats a one-time surge.
Turn every funded loan into your next referral
Digital Hayder builds review and follow-up systems for mortgage brokers: automated post-closing texts, agent partnership playbooks, and websites that turn review traffic into applications. Tell us about your pipeline and we will design the review engine around it.
Contact Us